I've never tried writing science fiction but this newsletter will probably be the closest I'll come. I don't blame you for being skeptical and finding this incredulous, but before you dismiss this topic, you should know Negative Rates have been studied and declared a possibility by the Bank of Canada if required. First, the monthly statistics.
Now for the fun, keep in mind we're not economists or bank policy experts so perhaps you should just consider my writing "For Entertainment Purposes only." Most people have heard something about the Negative Interest Rate Policy (NIRP) being adopted in Switzerland, Denmark, Sweden, the European Central Bank and just recently, Japan. Canada's current rate is 0.50%, not too far off the zero mark. What does NIRP mean? For you and I, it means that money in your bank accounts won't earn interest but you'll pay the bank for holding your money. The Bank Of Canada has already said that they're "confident that Canadian financial markets could also function in a negative interest rate environment." It's a strategy to try and reinvigorate an economy with other options exhausted. With regards to your mortgage borrowing rates, you can expect them to remain at these incredibly low rates but not go much lower.
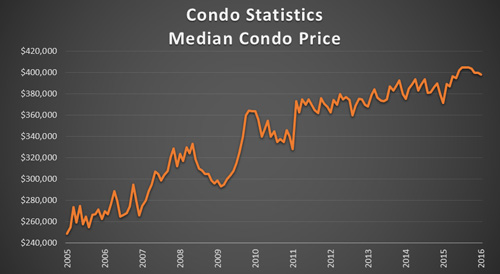
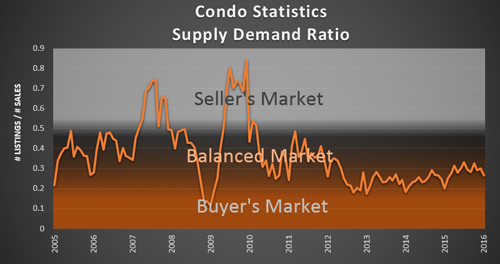
The median price was relatively flat at $398k. The supply/demand ratio continues to be flat in a balanced market.
Now for the fun, keep in mind we're not economists or bank policy experts so perhaps you should just consider my writing "For Entertainment Purposes only." Most people have heard something about the Negative Interest Rate Policy (NIRP) being adopted in Switzerland, Denmark, Sweden, the European Central Bank and just recently, Japan. Canada's current rate is 0.50%, not too far off the zero mark. What does NIRP mean? For you and I, it means that money in your bank accounts won't earn interest but you'll pay the bank for holding your money. The Bank Of Canada has already said that they're "confident that Canadian financial markets could also function in a negative interest rate environment." It's a strategy to try and reinvigorate an economy with other options exhausted. With regards to your mortgage borrowing rates, you can expect them to remain at these incredibly low rates but not go much lower.
So what would you do if your bank started to take a little out of your account every month? You'd be tempted to take your money out of the bank in cash and keep it under your mattress. In fact, Japan is experiencing a surge in the sale of home Safes right now. But expect the banks to be one step ahead of you. Have you heard the talk about abolishing the 500 Euro bill, 1000 Swiss Franc note and the 100 American bill by none other than Larry Summers? (former Secretary of the Treasury, former Chief Economist at World Bank and Harvard President). Their justification is that these high denomination bills are used to fund terrorism or evade taxes. Have you ever tried to take more than $3,000 in cash out of your bank? Most Canadian Banks will limit you to $3,000 per day and require a special order and a wait of several days for any larger amount. You should expect to be questioned why you're taking out so much cash.
If Canada gets negative rates one day, it will strongly encourage people to do something with the money in their bank accounts instead of letting it slowly erode away. I think people will either invest it in the stock market, use it to buy real estate or spend it... all good things for the economy, the banks and tax revenue for the government. I think it may put upwards pressure on real estate prices. Doesn't sound too bad after all, right?
It's too bad we wouldn't be able to protect our savings without taking on the risk that comes with any investment. But the more significant issue is why we're at this point in the first place. I believe the roots of the problem stem from the way our money is created in the first place... by creating debt through fractional reserve lending and having a purely fiat-based currency. Those topics take a while to understand but may end up being the most significant issues of our generation. I don't have the answers, and I don't think anybody knows how this will all play out, but there are strategies you can implement if you think negative interest rates are coming. It's your responsibility to educate yourself and take care of your affairs. A good start to understanding this big issue is a book by Jim Rickards called The Death of Money. Over long periods of time, Real Estate provides protection from inflation, diversification, and a roof over your head.
It's too bad we wouldn't be able to protect our savings without taking on the risk that comes with any investment. But the more significant issue is why we're at this point in the first place. I believe the roots of the problem stem from the way our money is created in the first place... by creating debt through fractional reserve lending and having a purely fiat-based currency. Those topics take a while to understand but may end up being the most significant issues of our generation. I don't have the answers, and I don't think anybody knows how this will all play out, but there are strategies you can implement if you think negative interest rates are coming. It's your responsibility to educate yourself and take care of your affairs. A good start to understanding this big issue is a book by Jim Rickards called The Death of Money. Over long periods of time, Real Estate provides protection from inflation, diversification, and a roof over your head.
Having said all this, it's much more important to keep up to date with Kanye and the Kardashians.